The best way to organize your personal finances efficiently
Your paycheck lands in your account and, for a moment, you breathe a sigh of relief. That feeling of being in control, though, doesn’t last long. The days go by and, before you know it, the money has simply vanished.
Your paycheck tends to vanish before the month ends because the money sits loose in your account with no clear job. Every expense becomes a new decision, and a tired brain picks the easiest path. The fix that works best is splitting your paycheck into categories on payday itself.
You blink and your plans to invest, save for the future or enjoy some guilt-free fun get pushed back, once again.
The mistake is almost never how much you earn. The real black hole in your finances is the lack of direction in the first 24 hours after payday. Leaving your money loose in your account is asking to be held hostage by your own impulses.
Why does the money disappear? How it works in our heads
Our brain is a machine that specializes in saving energy. When you don’t decide what each dollar will do the moment your paycheck arrives, you force yourself to make hundreds of financial decisions over the next 30 days. That wears your mind out. It’s often called decision fatigue.
To keep your brain from choosing the easiest (and most impulsive) path, you need to give your money a name. It’s like organizing a closet: if you have one drawer for shirts, another for pants and another for socks, you don’t waste time looking for what to wear. Everything has its place.
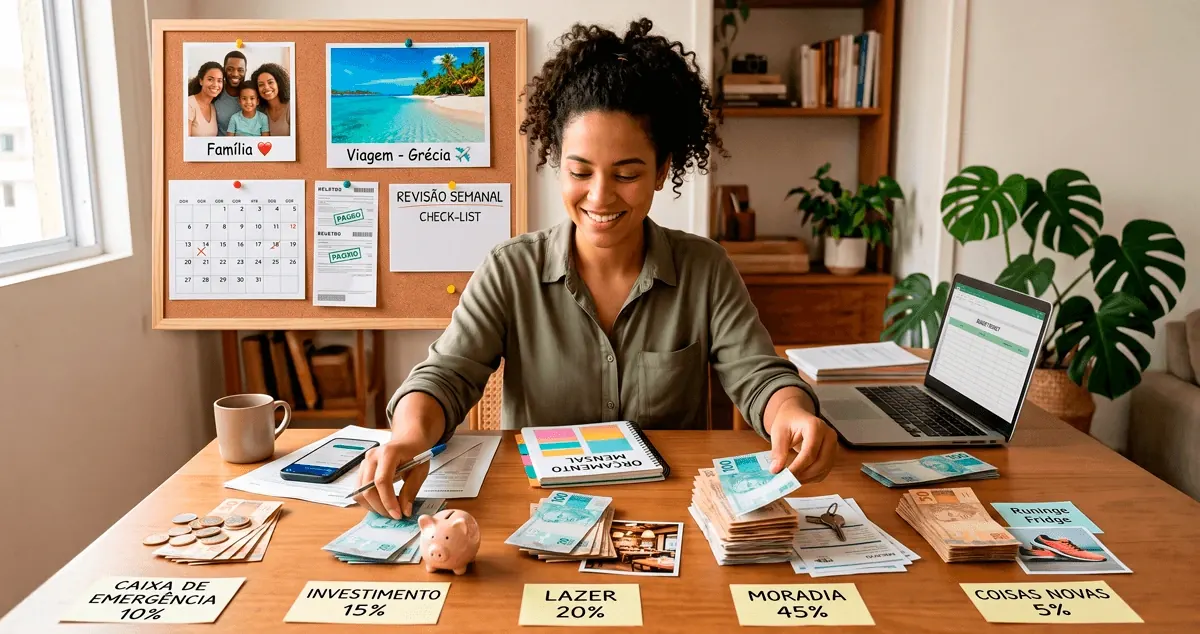
In practice, sitting down on day one and splitting up the total is what saves your month. Here’s a practical split you can use as a reference. Remember: this is just an opinion and a starting point. What matters most is adapting it to your reality, since costs like transportation and food, for example, change a lot if you get work benefits. Different salaries and more… every case is different. Take it only as a base:
- 10% Emergency fund: Money that sits still and is only there to put out real fires. The car that broke down, an unexpected illness, things that need to be fixed yesterday.
- 15% Investing: Your long-term view. It’s money earmarked for your future, the investments you study and enjoy making to improve your life down the road. Money for 5 to 10 years from now.
- 20% Fun: The budget for living. Spending time with people, going out to bars, the movies and enjoying social moments, with no guilt when the bill comes.
- 45% Housing: This is your big thermometer. It covers household bills, transportation and food. If this slice is going way over its percentage, it’s a warning sign that you’re spending too much on the basics. Mistakes that range from the neighborhood you chose to live in to ordering too much food delivery.
- 5% New things: Your fund for planned purchases. If the fridge breaks, the money comes out of the emergency fund. But if you want new sneakers, which aren’t urgent, this slice pays for the planned purchase.
- The rest (what’s left over): The final indicator. It gives you a clear idea of whether your month is very tight or whether your cash flow is healthy.
Why does it feel like you never get ahead?
The feeling of not getting anywhere financially rarely comes from a lack of effort at work. It comes from running a lot without knowing where you’re going.
The philosopher Seneca said: “If one does not know to which port one is sailing, no wind is favorable.”
When you split up your money on day one, you stop just reacting to bills. Organization isn’t a prison that keeps you from buying the good things in life; it’s exactly the practical tool that frees you to spend on what matters. It’s the moment you stop being swallowed by the month and start setting more of the rules for your own progress.
A note: surprises happen, and it’s normal to spend a month or two putting out fires. But see it as something to learn from, not something to repeat next month. Good luck with your finances!
To make your paycheck last until the last day of the month, here are three more reads:
- Organizing your money is laying one brick at a time, and here’s why putting things off costs so much.
- Interest also works in your favor when you start early. See the proof with just $200 a month.
- If your money vanishes and your head is always full of bills, see why we make more mistakes when we’re overloaded.
Editor’s note: We all have that friend who, by the 10th of the month, is already looking at their banking app with the sadness of someone watching a bad movie ending. Do their nervous system a favor and send them this article. Maybe they’ll realize the secret isn’t hoping there’s money left over, but giving it clear orders before it runs away.
Comments
No comments yet. Why not be the first?