Your relationship with money started before your first paycheck
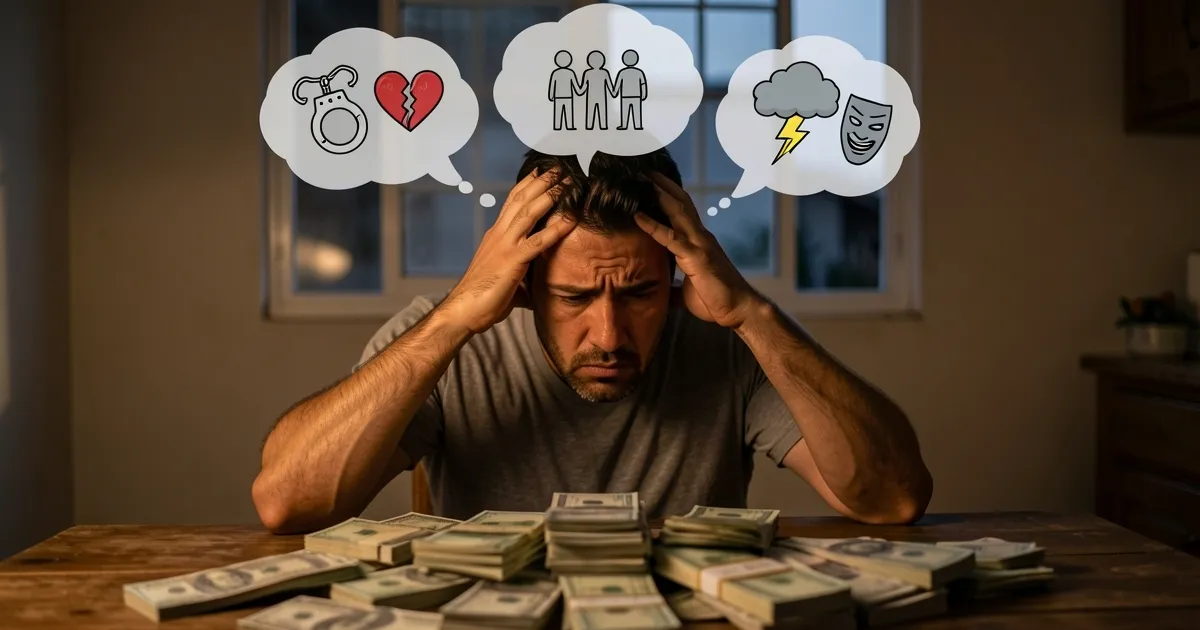
Your relationship with money is the way you think, feel and act around it. And almost nobody chose that relationship on purpose. It was put together in childhood, out of the things you heard at the dinner table, the scenes you watched at home and the scares your family went through. That’s why two people with the same salary can live completely different financial lives. The money coming in is only half the story; the other half is the eyes of the person receiving it.
Picture someone who has spent their whole life wearing their grandfather’s glasses. The prescription was made for other eyes, in another time. Everything looks a little crooked, a little blurry, and they assume that’s just how the world is. It has never crossed their mind that the problem might be the lens.
Money works in a very similar way.
How is our relationship with money formed?
Writer T. Harv Eker, author of Secrets of the Millionaire Mind, calls it your “money blueprint”, a kind of inner template we carry without noticing.1 According to him, that template is made of three ingredients.
The first is what you heard. “Money doesn’t grow on trees.” “Rich people are all crooks.” “That’s not for people like us.” A line repeated often enough in childhood becomes a truth in adult life, even if nobody remembers when they learned it.
The second is what you saw. If money was a reason for fights at home, there’s a good chance you avoid looking at your bank statement today. If your parents spent everything on payday, spending fast may simply feel normal.
The third is what you lived through. An eviction, a family business going under or a month when food ran short leave marks that speak louder than any spreadsheet.
Eker’s central idea is simple: thoughts lead to feelings, feelings lead to actions and actions lead to results. If we only work on the results, like cutting expenses or finding a side income, and leave the thoughts untouched, our finances tend to snap back to the same place, like a rubber band.
Why do we value money too much, or too little?
Researchers in financial psychology have a name for these beliefs: money scripts. They are almost automatic ideas, formed early, that help predict how a person will handle their finances.2 And they tend to pull toward two extremes.
On one side is the person who puts money on a pedestal. For them, more money would fix everything, and their own sense of worth seems to rise and fall with their balance. They keep chasing the next raise and never feel they’ve arrived.
On the other side is the person who pushes money away. They feel it’s ugly to want more, feel guilty when there’s some left over and, without realizing it, find a way to spend whatever comes in. From the outside it looks like detachment, but very often it’s fear.
Both are wearing the wrong prescription. One sees money as too big, the other as too small, and neither can see it at its actual size.
What is money actually worth?
Maybe the more honest question is a different one: what is money for in your life?
A large study on income and well-being helps put this in perspective. For most people, earning more keeps bringing more well-being, even at high income levels. But for people who are already unhappy for other reasons, past a certain point the extra money barely changes anything.3 In other words, money can improve life a lot, but it can’t fix what isn’t made of money.
Eker puts it in a similar way: money is extremely important in the areas where it works, like freedom, security and choices, and close to meaningless in the areas where it doesn’t, like love, purpose and being at peace with who you are.
Seneca said something along these lines almost two thousand years ago:
“It is not the man who has too little, but the man who craves more, that is poor.” (Seneca, Letters to Lucilius)
Can you change your relationship with money?
You can, and the first step is simply noticing that you’re wearing glasses. Many people never ask where that tight feeling in the chest comes from when they open their banking app, or the urge to spend right after getting paid. When someone can say “that’s my mother’s voice” or “that’s the scare from when my dad lost his job”, the lens already gets a little clearer.
The second step is changing the prescription slowly, by looking at the numbers calmly. Sometimes all it takes is seeing what a small habit costs over the years to look at money differently, and our cost of habits calculator runs that math in a minute.
Nobody has to throw away everything they learned at home. Plenty of those lessons are still good. The idea is just to check, one by one, which ones still fit your eyes today.
So here’s a question to carry with you this week. What did you hear most often about money as a child, and how much of your financial life today is still following it?
To keep adjusting the prescription, here are three more reads:
- If your lens keeps pushing decisions to later, here’s the price of putting things off.
- Once money stops looking like a monster, you start wondering how much it can grow, and the math shows that true wealth lies in what you do today.
- Looking at your statement feels much lighter when everything is in its place, so see the best way to organize your bills on payday.
Editor’s note: We all have that friend who says “money can’t buy happiness” every time the credit card bill arrives, and still checks their balance three times a day. Send them this article. Maybe it’s time to take their glasses in for a checkup.
Footnotes
-
Eker, T. H. (2005). Secrets of the Millionaire Mind: Mastering the Inner Game of Wealth. New York: HarperBusiness. ↩ source
-
Klontz, B., Britt, S. L., Mentzer, J. & Klontz, T. (2011). Money beliefs and financial behaviors: development of the Klontz Money Script Inventory. Journal of Financial Therapy, 2(1). ↩ source
-
Killingsworth, M. A., Kahneman, D. & Mellers, B. (2023). Income and emotional well-being: a conflict resolved. Proceedings of the National Academy of Sciences, 120(10), e2208661120. ↩ source
Comments
No comments yet. Why not be the first?